A couple in their fifties at a kitchen island, each with a laptop, the financial statements between them, mountains in the window

High-asset divorce: what the number is made of.

When the estate includes a business, real estate, equity compensation or a trust, a divorce is a financial-engineering problem with legal deadlines. It turns on preparation, valuation and tax, not the volume of paperwork.

  1. 01What makes an estate complex
  2. 02Five problems, five pages
  3. 03Disclosure and the five-year rule
  4. 04Keeping it private
  5. 05What people get wrong
  6. 06What to bring
  7. →Business valuation
  8. →Executive compensation
The fastest thing you can do today

Talk to us about your case.

303-507-5529

One call. A real person picks up, hears you out, and tells you how we would handle what you are facing and what to do first. No phone tree, no sales pitch, no obligation. Your first conversation is with our intake paralegal, who will get you to Aaron fast.

Rather write? Send a short note and during business hours we call you back within the hour.

A person answersMonday–Friday, 9 to 5No obligation

It isn’t the number. It’s what the number is made of.

A large estate made of salary and index funds divides easily. A moderate one made of a closely held company, three LLCs, unvested RSUs and a partial trust interest does not. Complexity comes from illiquidity, valuation disputes and embedded tax, not from the total on the balance sheet. And a dollar is not a dollar: a million in a brokerage account, a million in a retirement account and a million of home equity are three different after-tax numbers.

I spent seventeen years as a founding partner of a nine-attorney divorce litigation firm in Orange County representing CEOs, founders and public figures, then a decade as a general counsel closing deals and litigating the disputes that came with them, with a Georgetown LL.M. in taxation in between. I read a balance sheet the way an owner does, because I am one. I tax-effect every significant asset before we talk about who keeps what.

Boulder County estates have their own shape: startup equity, CU and federal-lab pensions and trust interests more often than operating companies, and the 20th Judicial District runs its cases on its own calendar and local rules. How that court works, step by step, is on the Boulder divorce page.

A high-rise residence at dusk with the city skyline in the window
The house is usually the photograph they remember. The file is the rest.

Every large estate holds three currencies: pre‑tax, Roth and taxable dollars. Divide them at face value and one side quietly takes the other’s tax bill.

Contact me now.
A business, a portfolio or a trust in the estate? Three fields, thirty seconds. During business hours my office calls you back within the hour.

What makes an estate complex.

Not the size. The ingredients. Each one below has its own valuation problem, its own tax problem and its own page.

Colorado divides marital property as the court finds just under C.R.S. § 14-10-113, not on an automatic 50/50. Judges have broad discretion, which means outcomes are driven by how assets are identified, valued and presented. In a complex estate that is three separate jobs: finding everything, putting a defensible number on each thing as of the right date, and pricing what each thing is worth after tax to the spouse who keeps it.

The order matters. Classification comes first, then valuation, then tax, then the division, and then maintenance on the income that is left, without counting the same dollars twice. Most disputes in these cases are not about the percentage; they are about whether a step was skipped.

What makes it complex

The ingredients.

  • A closely held company, a practice or a partnership interest
  • Multiple entities: LLCs, holding companies, real estate in more than one state
  • Unvested RSUs, options, deferred compensation, carried interest
  • A trust interest, as beneficiary or as settlor
  • A spouse who ran the finances, or a spouse who did not
  • Digital assets and accounts in other names
What does not

The easy version.

  • A large number in index funds
  • A high salary with nothing else
  • A house with a mortgage and two retirement accounts
  • Assets that are already liquid and already taxed

Five problems, and how each one is actually solved.

Each has its own page. This is the map.

01
A lawyer and a forensic accountant at a conference table, the binders and a calculator between them, the analysis on her laptop
The business

Value it right, and count the dollars once.

The company usually stays with the operator; what is divided is its value, and the valuation is the number the rest of the case has to live with. Income approach or market approach, normalized owner compensation, personal versus enterprise goodwill, and the marketability discount are where the experts diverge. Then the second problem: the same dollars should not fund the valuation and a maintenance award twice.

What I do
  • Retain the valuation expert early and shape the engagement
  • Read the report as an operator, not a litigant, and find the assumption that moves the number
  • Run maintenance on the income the valuation leaves, not on top of it
02
An RSU vesting calendar, a bonus letter and a deferred compensation plan document
Equity compensation

Property, or income? The line worth arguing.

Unvested equity is one of the hardest problems in a high-asset case: part property, part future compensation, and the line between them is negotiable. Vesting schedules, grant purposes and tax treatment all matter, and whether an award is divided as property or counted as income for support changes the whole case. Options, RSUs, deferred compensation and carried interest each carry a different tax character, and the tax character is not a footnote; it is the number.

What I do
  • Inventory every grant with its date, purpose, vesting and tax character
  • Argue the property-or-income line on the facts of each grant
  • Price the after-tax value of what each side keeps
03
A leather-bound family trust instrument with a wax seal
Trusts

The instrument, not the balance, decides.

What a beneficiary actually has is what the trustee can be made to do. A discretionary interest, a mandatory distribution, a spouse who is also a settlor, a trust that paid the household’s expenses for a decade: each is a different case, and the document controls. The balance on the statement is where the analysis starts, not what it is worth.

What I do
  • Read the instrument before anyone argues about the balance
  • Trace what the trust actually paid for during the marriage
  • Decide whether the interest is property, income, or neither, on the terms
04
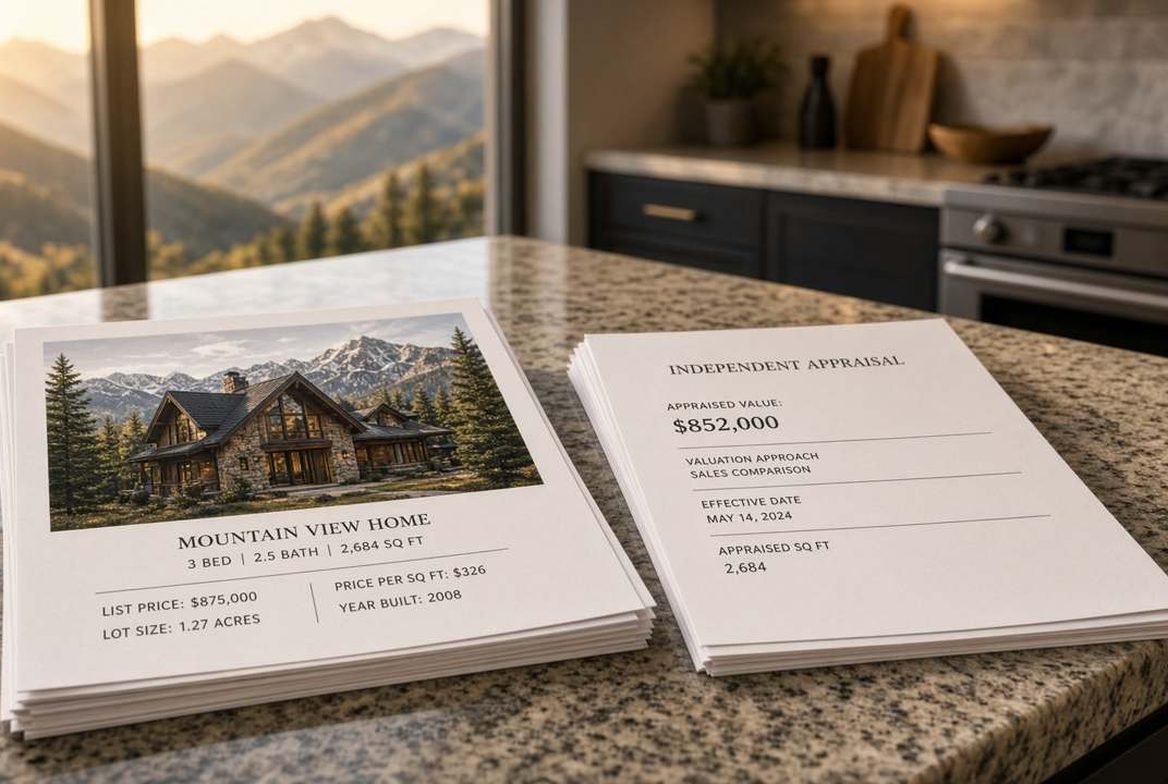
A listing packet and an appraisal on a kitchen counter, a foothills house in the window
Real estate

The listing is not the value. The appraisal is not the proceeds.

A primary residence, a mountain house, rentals in an LLC, a commercial building with a partner: each carries a different valuation date question, a different mortgage, and a different after-tax number when it is sold or kept. The house is also the one asset people fight about for reasons that have nothing to do with value. I keep those two conversations separate and price both.

What I do
  • Appraise as of the right date, with the right assumptions
  • Model keep-versus-sell after tax, with the refinance risk priced
  • Structure who keeps which property so the cash flow works after the decree
05
A hardware wallet beside a cryptocurrency disclosure statement and attorney notes
Digital assets

Findable, valuable, divisible.

Exchange accounts, hardware wallets, staking income and tokens held in other names are all marital property if acquired during the marriage, and all of them leave a trail: exchange statements, tax reporting, transfers from bank accounts, on-chain records. The addresses are the inventory; the wallet is just the key. Valuation dates matter more here than anywhere else in the estate.

What I do
  • Subpoena the exchanges and trace the fiat on-ramps
  • Fix a valuation date and a method the court will accept
  • Draft the transfer mechanics so the division actually happens

Disclosure, and discretion.

One is mandatory and continuing. The other is a decision made before the petition is filed.

A forensic accountant at a conference-room desk reading a schedule from an open binder, a highlighter and calculator beside her, the spreadsheet on her laptop
Disclosure

Complete disclosure, and the five-year rule.

Colorado imposes an affirmative, continuing duty of full financial disclosure. Colorado’s disclosure rule, C.R.C.P. 16.2, requires a sworn financial statement, mandatory disclosures and supporting documents from both spouses within 42 days of service. A division based on materially incomplete disclosure can be reopened and reallocated on a motion filed within five years of the decree. Hiding assets is not a durable strategy; neither is assuming the other side’s disclosures are complete. Part of my job is making sure they actually are.

What I do
  • Build your disclosure like testimony, because it is
  • Audit theirs against the tax returns, the bank records and the entities
  • Use the forensic accountant early, when the trail is still warm
A sealed envelope on a desk, window blinds drawn against the city
Privacy

Keep it private where possible.

Discretion matters to the people I represent. Where appropriate, disputes are resolved through private mediation or arbitration rather than open court, sensitive financial exhibits are handled to limit public exposure, and what goes into the caption and the file is thought about from the first filing. If your name means something in this town, the process should respect that. Total secrecy is not honest to promise; substantial discretion is achievable.

What I do
  • Decide the forum, private or public, before the petition is filed
  • Handle financial exhibits so they are seen by the people who need to see them
  • Litigate with discipline, because conduct is what ends up in a public record

What I tell every client with a complex estate.

Six things, in the order they come up. The first one is where most of the value is won or lost.

A high-rise residence at dusk
  1. Retain the experts early.

    The valuation expert, the forensic accountant, the tax advisor if it is not me. Weeks of lead time change the answer; a report finished the week before the hearing gets taken apart.

  2. Temporary orders set the trajectory.

    Who runs the business, who pays what, what the status quo looks like for a year. Handle them as if they were permanent, because they tend to be.

  3. Tax-effect every significant asset.

    Before anyone talks about who keeps what. The same half is worth different amounts depending on what it is made of.

  4. Disclose everything.

    The duty is mandatory and continuing, an omitted asset reopens the case for five years, and credibility is the one asset you cannot replace.

  5. Keep the business running normally.

    The injunction allows the ordinary course. A new entity, an unusual distribution or a sale during the case is evidence against you.

  6. Decide on privacy before the petition.

    Private mediation or arbitration, sealed exhibits and disciplined conduct are decisions made at the start, not repairs made later.

Six things people get wrong.

Colorado is a 50/50 state.

Equitable, not equal. The court divides marital property as it finds just, with broad discretion. Equal is common; it is never automatic.

I built the company, so it’s mine.

A business started or grown during the marriage is marital property. The operator usually keeps it; the value is divided, on the evidence of the valuation.

My K-1 is my income.

The K-1 is a tax allocation. Income for maintenance and support is normalized: distributions, retained earnings, perks and a peak year are all argued.

Unvested RSUs aren’t property.

They can be, in whole or in part, depending on when and why they were granted. The line is negotiable and it moves the whole case.

We can keep everything private.

Substantial discretion is achievable through private mediation or arbitration and careful handling of exhibits. Total secrecy is not honest to promise.

A bigger team wins.

A prepared lawyer who reads the balance sheet as an owner, with the right two experts, wins. Volume of paperwork is not a strategy.

What to bring, and what to settle first.

Before the first meeting

Bring the estate.

  • Three to five years of personal and business tax returns, with K-1s
  • Financial statements for every entity, and the operating agreements
  • Every grant agreement: options, RSUs, deferred compensation, carried interest
  • Trust instruments and the last two years of trust statements
  • Deeds, mortgages and appraisals for every property
  • Brokerage, retirement and bank statements, current, in either name
  • Any prenuptial or postnuptial agreement
Before you negotiate

Six things settled first.

  • Every asset classified and every entity mapped
  • The valuation expert retained, and the valuation date fixed
  • Income normalized for maintenance and support, once, not twice
  • Every proposed division run after tax
  • The forum decided: private mediation or arbitration, or the court
  • Temporary orders that keep the business running and the status quo yours

Divide an estate at face value and you can quietly hand one side hundreds of thousands of dollars of the other’s tax bill.

If the estate is complex, start the preparation before the filing →

Equitable division · Disclosure · Experts and the order of work · Settling from strength

Equitable division rewards the prepared.

Colorado divides marital property equitably under C.R.S. § 14-10-113: what is fair under the circumstances, not an automatic 50/50, after weighing each spouse’s contribution, the property set apart to each, the economic circumstances at division, and changes in the value of separate property. Judges have broad discretion, which means outcomes are driven by how assets are identified, valued and presented. In a complex estate that is the whole case.

Disclosure.

C.R.C.P. 16.2 requires complete, affirmative financial disclosure from both spouses, and the duty continues through the case. A division based on materially incomplete disclosure can be reopened and reallocated for up to five years after the decree (C.R.C.P. 16.2(e)(10)). The forensic work that makes the other side’s disclosures answerable is described on hidden assets and forensic discovery.

Experts, and the order of work.

Classification, then valuation, then tax, then division, then maintenance and support on the income that remains. The valuation expert and the forensic accountant are retained early and directed to the questions that move the number. The same dollars are counted once: a business valued on its earnings does not also produce those earnings as income for maintenance without an adjustment, and the record has to show the court where the line is.

Settle from strength. Keep it private where possible.

I prepare every case as though it will be tried: the right experts retained early, temporary orders handled with care because they set the trajectory of the whole case, and a record built from day one. That preparation is what produces strong settlements. Where appropriate, disputes are resolved through private mediation or arbitration rather than open court, and sensitive financial filings are handled to limit public exposure. See privacy and discretion and mediation and litigation.

Run the numbers

What clients with significant assets ask first.

Is Colorado a 50/50 state?

No. Colorado divides marital property equitably, fairly under the circumstances, considering contributions, economic circumstances and the nature of the assets. Equal happens; it is never automatic.

How are stock options and RSUs handled?

Unvested equity is one of the hardest problems in a high-asset case: part property, part future compensation, and the line between them is negotiable. Vesting schedules, grant purposes and tax treatment all matter. It is exactly the kind of issue that decides whether a settlement is actually fair.

Will my spouse get half of my company?

Usually not the company. Colorado divides the value of a marital business, not the business itself; the operator typically keeps the company and the other spouse is compensated with other assets or over time. The fight is the valuation, and whether the same dollars are counted once in the value and again in maintenance.

How is a business valued in a divorce?

By a qualified expert, using income, market or asset approaches as the business warrants, as of a valuation date the court sets. Personal goodwill, owner compensation, retained earnings and the discount for lack of marketability are where the opinions diverge, and where a lawyer who can read the report earns his fee.

Can our divorce stay out of the public eye?

Much of it can. Private mediation and arbitration, careful handling of financial exhibits, sealing or suppression where the rules allow it, and disciplined litigation conduct all limit exposure. Total secrecy is not honest to promise; substantial discretion is achievable.

How long does a high-asset divorce take?

Longer than the ninety-one-day minimum, because valuation and disclosure take time to do right. Most complex cases run several months to a year or more. The pace is set by the experts’ timelines and the court’s case management order, and by whether the other side’s disclosures are complete.

Do I need a forensic accountant?

If there is a business, variable income, a trust, or a spouse who ran the finances, usually yes, and early. The forensic work is what turns a K-1 into income, a set of statements into a tracing file, and a suspicion into an exhibit. It is also what makes the other side’s expert answerable.

Keep reading

Where to go next.

The next page in this chapter, the pages that belong with it, and the blog posts on the same question.

From the blog, on this topic

All articles from the blog →

If your estate is complex, the preparation should start before the filing does.

A consultation is a working session, in person in Greenwood Village or by video: we go through the balance sheet, what each asset is made of, and I tell you which experts to retain and in what order. Your note reaches my office directly; during business hours we call you back within the hour, run the conflicts check, and set the meeting.

The fastest thing you can do today

Talk to us about your case.

303-507-5529

One call. A real person picks up, hears you out, and tells you how we would handle what you are facing and what to do first. No phone tree, no sales pitch, no obligation. Your first conversation is with our intake paralegal, who will get you to Aaron fast.

Rather write? Send a short note and during business hours we call you back within the hour.

A person answersMonday–Friday, 9 to 5No obligation