42 days
The disclosure clock
Sworn financial statement and the mandatory disclosures, without a request, within forty-two days after service; a continuing duty to supplement to the decree.
Two operating companies and a holding LLC. A partnership interest with capital calls. Deferred compensation that pays in four years. A trust his father funded. A rental in Scottsdale and a condo in Cabo. Nothing about the Colorado statute changes for this estate; everything about the proof does. The rule gives you forty-two days of mandatory disclosure and a continuing duty to supplement, discovery tailored to the case, one expert per issue on a fifty-six-day clock, and a valuation date fixed by statute. This page is how the case is sequenced, what has to be established for each kind of asset, and what the court will and will not do.
Talk to us about your case.
303-507-5529One call. A real person picks up, hears you out, and tells you how we would handle what you are facing and what to do first. No phone tree, no sales pitch, no obligation. Your first conversation is with our intake paralegal, who will get you to Aaron fast.
Rather write? Send a short note and during business hours we call you back within the hour.
Value. Characterize. Tax-effect. Then divide. The order is the strategy.
A complex estate is not divided; it is established. Before a judge can apply the statute’s factors, someone has to prove what the assets are, which spouse’s they are, what they are worth on the valuation date, and what they are worth after the tax the eventual owner will pay. Each of those is a separate question with its own evidence, and the side that takes them in order controls the case. The side that skips to the division, with an opening offer built on a guess about the company, spends the next year defending the guess.
I spent seventeen years doing this work for founders, executives and their spouses in Orange County, then a decade as a general counsel on the client’s side of the table, buying and selling the kinds of companies that show up in these estates, and I hold a Georgetown LL.M. in taxation. What follows is the method: the disclosure rule and its deadlines, the discovery the Colorado Supreme Court has said a family court will allow, the valuation rules the appellate courts have set, and the asset-by-asset questions that decide a complex case. The High-Asset Divorce page covers the size of an estate; this page covers its structure.
Sworn financial statement and the mandatory disclosures, without a request, within forty-two days after service; a continuing duty to supplement to the decree.
The parties shall attempt to select one expert per issue; reports fifty-six days before the hearing, rebuttal twenty-one days later.
An asset misstated in or omitted from the disclosures can be reallocated on a motion filed within five years of the decree.
Complexity is a list of kinds, and each kind has a different question. The first week of a complex case produces this map.
| The asset | The question it raises | The proof | The page |
|---|---|---|---|
| Operating companies and holding entities | Marital or separate; what standard of value; whether a discount applies; who keeps it and how the other spouse is paid | Three years of financial statements plus year-to-date, tax returns, the operating agreement, the cap table, compensation records; an appraiser | Business Valuation · Business Owner Divorce |
| Professional practice | Goodwill and who can own it; reasonable compensation; the buy-sell formula | Production reports, the partnership agreement, buy-in and buy-out history | Professional Practices |
| Equity and deferred compensation | Enforceable right; what the grant was for; the tax at vesting; property, income or both | The plan document and every grant agreement; the equity-portal history; the deferred-compensation plan and elections | Equity Compensation · Executive Compensation |
| Trust interests | Vested remainder, discretionary, or revocable; appreciation during the marriage | The trust instrument, the trustee’s accountings, distribution history | Trust Interests |
| Partnership and fund interests | Capital account, distributions, unfunded commitments, carried interest; whether an enforceable right exists yet | The LPA, K-1s, capital-call notices, the fund’s valuation letters | Income Determination |
| Real estate, here and elsewhere | Character and appreciation; valuation; selling costs only if a sale is real; how out-of-state and foreign property is reached | Deeds, appraisals, loan documents, entity ownership | Real Estate |
| Retirement plans and pensions | Premarital balance and its growth; QDRO, PERA agreement, military rules; survivor benefits | Statements at the marriage date and the decree date, plan documents | Retirement Assets |
| Separate-property claims | Tracing gifts, inheritances and premarital assets through exchanges and accounts; the appreciation that is marital anyway | Account histories back to the source, closing statements, gift letters | Separate Property |
| Digital assets | Existence, custody, valuation, tracing across wallets and exchanges | Exchange statements, wallet addresses, blockchain records | Cryptocurrency & Digital Assets |
An estate with three of these is a complex case; an estate with six is a year of work. The map decides which experts are needed, and in what order they have to finish.
Colorado’s family-case rule is built around a duty most litigants have never read. Parties to domestic relations cases owe each other and the court a duty of full and honest disclosure of all facts that materially affect their rights and interests.
| The provision | What it requires | What it means in a complex case |
|---|---|---|
| The initial status conference | As soon as practicable but no later than forty-two days from the filing of the petition, with all parties and counsel attending, unless a stipulated case-management plan is filed. | The conference where the discovery plan, the expert plan and the hearing dates are set. A side that arrives with the map of the estate sets the agenda. |
| Mandatory disclosures | Without a formal discovery request, the mandatory disclosures and a completed sworn financial statement within forty-two days after service of the petition or a post-decree financial motion. | The fourteen categories below, for every entity and account. The business financial statements alone are a box. |
| The continuing duty | A party is under a continuing duty to supplement or amend any disclosure in a timely manner, governed by the civil rule on supplementation. | The offer for the company that arrives after the disclosures, the bonus declared in December, the grant awarded the week before the hearing: all of it, to the decree. |
| The certificate and the sanctions | A certificate of compliance is filed with the court; nondisclosure carries sanctions; undisclosed witnesses and exhibits are excluded absent good cause. | The certificate is a sworn statement that becomes the exhibit in a reopening motion five years later. |
| Discovery limits | Pattern interrogatories and requests for production, plus ten additional interrogatories and ten additional requests for production, each a single question; depositions of parties and non-parties; all discovery completed not later than twenty-eight days before the hearing. | Ten extra requests is not many. They are spent on the specific: the general ledger, the capital-account history, the trustee’s accountings, the grant agreements. |
| Experts | The parties shall attempt to select one expert per issue; expert reports provided fifty-six days before the hearing; rebuttal reports twenty-one days thereafter; the trial management certificate seven days before the hearing. | A joint valuation expert saves a six-figure fight and is what the rule wants; a party who distrusts the joint report may retain a rebuttal expert on the twenty-one-day clock. |
The mandatory-disclosure list: the sworn financial statement; three years of federal returns with all schedules; personal financial statements, statements of assets or liabilities and credit or loan applications from the last three years; business financial statements for three fiscal years plus year-to-date; real estate title and value documents; debt documents; investment statements; documents identifying each employment benefit and its current value; retirement plan statements and summary plan descriptions; bank statements; income documentation; and the children’s child-care, insurance and expense records.
The mandatory disclosures were designed by people who understood that a tax return and a loan application are two sworn stories about the same money.
Returns are written to minimize income. A business owner’s tax return is a document prepared to pay as little tax as legally possible, and it says so on every schedule: accelerated depreciation, expensed perquisites, retained earnings that never became a distribution. It is the starting point for income and value, never the answer.
Loan applications are written to maximize it. The personal financial statement the same owner gave the bank eighteen months ago, to refinance the building or extend the line of credit, lists every asset at its highest defensible value and every income stream at its best. The rule requires production of every such statement from the last three years for a reason: the two documents, side by side, bracket the truth, and an owner who swore to both has to explain the difference under oath.
The certificate is the trap. Compliance is certified to the court. A party who certifies compliance and withheld the financial statements, the loan applications or the appraisals has created the record for a reopening motion, which needs no proof of intent, within five years of the decree. The Reopening page covers what happens then.
The Colorado Supreme Court drew the line in 2017, in a case about a subpoena to a spouse’s employer, and it is the line every complex case is argued inside.
Discovery in a Colorado divorce is tailored and proportional: a focused subpoena for what the valuation requires is granted; a fishing expedition through a company is not.
The rule. In In re Marriage of Gromicko, 2017 CO 1, the Supreme Court reversed a broad third-party discovery order and held that the family-case rule requires active case management from filing to resolution, with discovery tailored to the needs of the case under the civil rules’ proportionality standard. Discovery in a divorce is not open season on a spouse’s company; it is what the case needs, weighed against the burden.
What that means in practice. A subpoena to the company for the general ledger, financial statements, compensation and distribution records, the operating agreement and the cap table is proportional in nearly every valuation case. A demand for every officer’s email for five years is not. A request for a fund’s capital-account statements and valuation letters for the spouse’s interest is proportional; a demand for the fund’s investor list is not. The lawyer who asks for what the appraiser needs, and can say why, gets it; the lawyer who asks for everything gets a hearing about proportionality and a narrowed order.
Third parties and protective orders. Business partners, trustees, employers and banks respond to subpoenas, and they resist them. A stipulated protective order that limits use of the records to the case, restricts who may see them and requires their return usually resolves the objection, and it protects the business from the divorce becoming a source for competitors. The Privacy page covers what stays out of the public file.
Depositions. The rule permits depositions of parties and non-parties without a stated cap. In a complex case the useful ones are the owner-spouse on the entity structure and compensation, the company’s controller, and the trustee. Depositions of the appraisers are usually unnecessary once reports are exchanged.
Three rules the appellate courts have set, and each decides money in a complex estate.
| The rule | What the courts have held | What it means |
|---|---|---|
| The valuation date | Property shall be valued as of the date of the decree or as of the date of the hearing on disposition of property if such hearing precedes the date of the decree. Assets and debts share one date. | A company that grew during the case is valued as it stands at the hearing; the spouse who delays a hearing while the business rises or falls is choosing a number. |
| Marketability and minority discounts | Trial courts may, in their discretion, choose to apply a marketability discount when valuing a spouse’s ownership interest in a closely held corporation in a dissolution proceeding. The no-discount rule of the corporate dissenters’ statute does not extend to divorce. | A thirty-three percent discount on an LLC interest was affirmed in Thornhill. Whether a discount applies is proved with evidence of the interest, the agreement and the market, and argued from the standard of value the appraiser adopted. |
| Appreciation of separate property | A premarital, gifted or inherited asset is marital to the extent its present value exceeds its value at the marriage or at acquisition; the increase is measured asset by asset, without netting declines in other separate assets. | The spouse claiming separate property proves the value at the start and traces it to the end; the growth in between is divided. |
| Tracing through exchanges | Property acquired in exchange for separate property remains separate, if the exchange is proved; property acquired during the marriage is presumed marital regardless of title. | Account histories back to the source, closing statements, gift letters. Commingled funds that cannot be traced are marital. The Separate Property page covers the method. |
| Trust interests | A vested remainder in an irrevocable trust is property, separate as a gift, with appreciation during the marriage marital; a discretionary interest, or one under a revocable instrument, is neither property nor an economic circumstance. | In Smith (2024) a family trust with a third party’s power of appointment was held to be nothing the court could consider. The instrument decides. |
| Expectancies | A discretionary bonus not yet awarded is a mere expectancy and not property, though it may be income for support. | Carried interest, unfunded profits interests and undeclared bonuses are analyzed under the enforceable-right test, asset by asset. |
Colorado has not adopted a single standard of value for divorce. The appraiser’s choice between fair market value and value to the owner is the argument beneath every discount fight, and the Business Valuation page sets it out.
Five kinds of asset that appear in most complex Denver estates, and the question each one turns on.
Draw the entity chart before anyone is valued, and settle reasonable compensation once, because it sets both the company’s value and the owner’s income.
Which entity owns what. A founder’s estate is usually a holding LLC that owns the operating company, the building through a second LLC, and the equipment through a third, with intercompany loans between them. The chart is drawn first, from the operating agreements and the returns, because the valuation depends on which entity the appraiser is valuing and whether the building is inside or outside it.
Reasonable compensation. Every valuation by capitalized earnings turns on what a non-owner would be paid to run the company, and every support calculation turns on the same figure from the other side. The owner who argues a high salary to shrink the company’s value has argued a high income for maintenance. The Income Determination page covers the add-backs.
Retained earnings and distributions. Pass-through income from a closely held company is income for support unless the owner is a passive minority investor; earnings retained for a genuine business need are argued as an exception, with the company’s books, not a story.
Deferred compensation is divided by offset or a pay-when-received clause; fund interests are allocated line by line; a trust is property only if the instrument makes the interest enforceable.
Nonqualified deferred compensation. It cannot be divided by a QDRO and most plans forbid assignment; the tax code limits when a plan can pay anyone. It is divided by offset or by an if-as-and-when clause under which the employee remits the former spouse’s share when the plan pays, net of tax, and the IRS has ruled that vested deferred compensation transferred incident to divorce is taxed to the former spouse when paid.
The fund interest. A limited partnership or private-equity interest carries a capital account, a schedule of distributions, an unfunded commitment and, for a general partner, carried interest. The capital account and distributions are valued from the fund’s letters; the unfunded commitment is a liability someone has to bear; the carry is an expectancy until it is earned, with no Colorado appellate decision on point. The agreement allocates each one expressly, including who funds future capital calls.
The trust. The instrument is read first: a vested remainder is property, and its growth during the marriage is marital; a discretionary interest with a third party’s power of appointment is nothing. Distributions actually received are income. The trustee’s accountings are discoverable to the extent the interest is at issue, and a protective order usually accompanies them.
Out-of-state and foreign property is reached through the spouse, not the land: the court orders the conveyance and enforces it, or prices the asset into the Colorado division.
The court’s reach. A Colorado court cannot itself pass title to land in Arizona; the Supreme Court of the United States settled that in 1909. What it can do is order the spouse who holds title to sign the deed, and enforce the order by contempt. The decree is drafted with the conveyance language the other state’s recorder expects, and the deed is signed at the decree, not later.
Foreign property. The Cabo condo is held through a bank trust, the Paris flat through a civil company; the registries of those countries decide what a Colorado decree can accomplish there. Where the foreign registry will not honor a Colorado order, the spouse who keeps the property pays for it with Colorado assets, and the decree says what happens if the transfer fails.
Digital assets. Existence and custody first: exchange statements, wallet addresses, the blockchain itself. Value on the decree date, with the volatility handled by an in-kind division where the parties can each hold. The Cryptocurrency page covers the tracing.
Two rules that shape every complex estate from the day the petition is served.
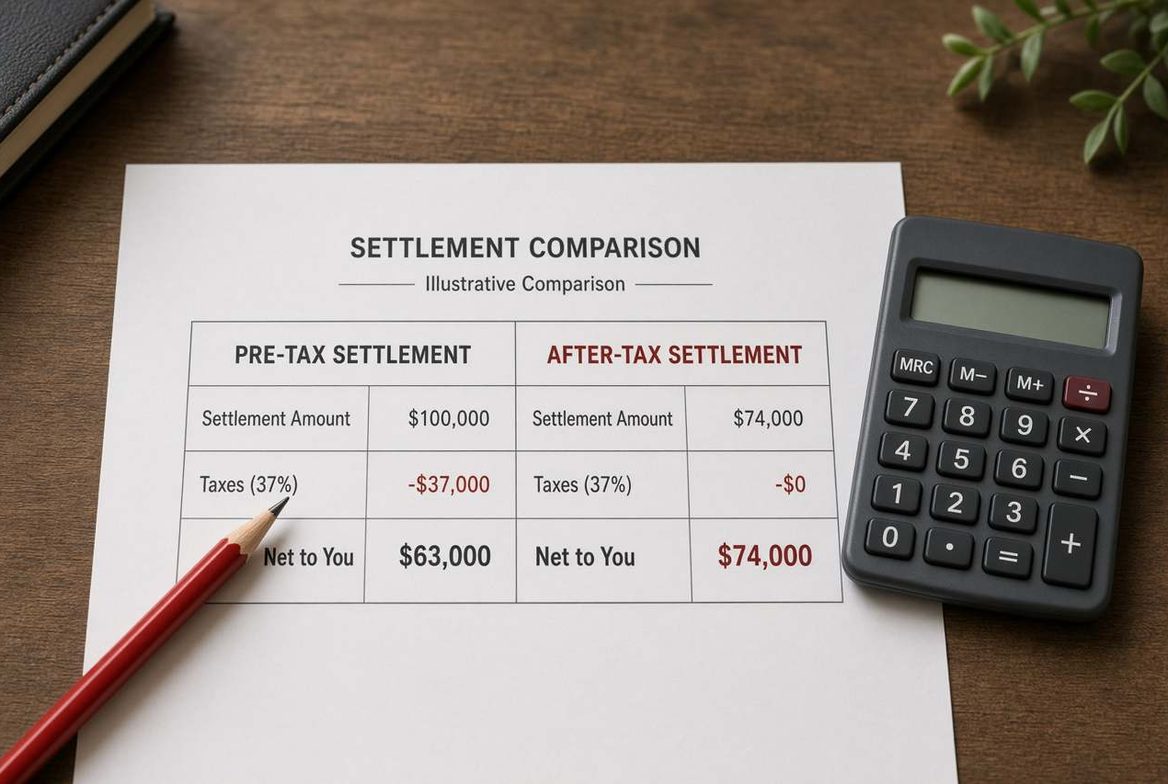
A court tax-effects an asset only on evidence of a real, imminent liability and its rate; an agreement can price every asset after tax, and in a complex estate it should.
The court’s rule. Colorado courts value assets gross unless there is evidence that the tax will actually be incurred and evidence of the rate. A court refused to reduce retirement funds for early-withdrawal tax where the withdrawal was hypothetical and entirely within the husband’s control, and refused to deduct capital-gains tax from real estate where there was no evidence of a potential sale. A court that reduced an award for tax without evidence of the amount or the rate was reversed.
The negotiator’s rule. An agreement can do what a court will not: price every asset at what its owner will keep after tax. A pre-tax retirement dollar, a Roth dollar, a dollar of built-in gain in a company, a dollar of cash: four different values, and an estate divided at face value hands one spouse the other’s tax bill. The Tax Strategy page sets out the method; on this page the point is that the evidence for it, the rates and the liabilities, is assembled during discovery, not argued from memory at the hearing.
| The automatic temporary injunction | What it restrains, from service to the decree |
|---|---|
| Marital property | Both parties are restrained from transferring, encumbering, concealing or in any way disposing of any marital property without the consent of the other party or an order of the court, except in the usual course of business or for the necessities of life, and each must notify the other of any proposed extraordinary expenditure and account to the court for all extraordinary expenditures made after the injunction is in effect. |
| The business | The usual course of business continues: payroll, vendors, ordinary distributions. A sale of the company, a new partner, a change in the owner’s compensation, or a special distribution is an extraordinary act that needs consent or an order, and the accounting duty attaches to it. |
| Insurance | Without fourteen days’ advance notice and written consent or an order, neither party may cancel, modify, terminate or let lapse any health, homeowner’s, renter’s, automobile or life insurance covering the parties or the children. |
| The children | Neither party may remove the children from the state without consent or an order. |
| What it does not do | It does not freeze accounts, stop a business from operating, or require court approval of ordinary life. It becomes an order of the court on service, and a spouse who moves marital assets after it has violated an order, with the accounting and the credibility consequences that follow. |
One lawyer, the right experts, no entourage. And an order of operations that does not change from case to case.
| Who | What they do | When they are needed |
|---|---|---|
| The forensic accountant | Traces funds through accounts and entities; reconstructs income from the books; finds what the returns do not show; supports a separate-property claim or a dissipation claim | When money moved between entities or accounts, when income is disputed, when assets may be missing; engaged early, before the discovery plan is set |
| The business appraiser | Values the company or the professional practice under a stated standard of value; addresses reasonable compensation and discounts | Every case with an operating company; ideally as a joint expert, with a rebuttal expert reserved |
| The real estate appraiser | Values each parcel as of the decree; supports or rebuts a claim about a premarital home’s value at the marriage | Every parcel the parties cannot agree on; historical appraisals for separate-property claims |
| The tax adviser | Prices each asset after tax; models the settlement alternatives; structures transfers under the divorce provisions of the code | Before any settlement proposal is made, and again before the agreement is signed |
| The vocational evaluator | Establishes what a spouse could earn where income is imputed | Maintenance and support fights over a spouse who is not working to capacity; the Vocational Assessment page |
| Counsel | Draws the map, runs the discovery plan, holds the experts to the rule’s deadlines, negotiates from the trial file, tries the case | From the first week |
The rule asks the parties to attempt to select one expert per issue. A joint appraiser, jointly instructed, is the largest single saving in a complex case, and a party who disagrees with the joint report keeps the right to a rebuttal expert on the twenty-one-day clock.
The entity chart, the account list, the asset list by kind, and the questions each one raises. Produced in the first two weeks from the returns and the operating agreements, before the status conference.
The forty-two-day disclosures, checked against the map; the ten additional requests spent on what the appraiser needs; the subpoenas to the company, the fund and the trustee, with protective orders; the joint expert proposed.
Separate-property tracing and the marital appreciation; the appraisals on the statutory date; the discounts argued from the standard of value; expert reports fifty-six days before the hearing, rebuttals twenty-one days later.
Every asset priced after tax; the alternatives modeled; a proposal built from the trial file. Most complex cases settle here, in mediation, because the numbers are finally on the table.
A permanent orders hearing of one to three days on the contested assets, with the experts; or a separation agreement that carries the transfer mechanics, the tax allocations, the deferred-compensation and equity clauses, and the security for every deferred payment.
| Stage | In my experience | What stretches it |
|---|---|---|
| Map and disclosures | Six to eight weeks | An owner who produces returns but not the financial statements or the loan applications |
| Discovery and subpoenas | Three to five months | Third-party objections; a fund or trustee that resists; a proportionality hearing |
| Valuation reports | Two to four months, overlapping | A joint expert both sides second-guess; a second appraisal; a company in transition |
| Mediation to agreement | One to two months | A tax model neither side has run; deferred payments nobody has secured |
| Permanent orders hearing | Nine to fourteen months from filing | The court’s calendar; a multi-day setting; a continuance for a late report |
Ranges from my own cases in the Denver metro courts; the case management order and the court’s calendar control the dates.
Six things, in the order they come up. Not legal advice for your case; the mistakes I have watched for thirty years.
Value, characterize, tax-effect, then divide. A proposal built before the company is valued and the separate property is traced is a proposal you will spend a year defending.
They are mandatory, and the other side will get them. The owner who tries to withhold them turns a valuation dispute into a credibility case, and a reopening case five years later.
The Supreme Court made discovery proportional. A focused subpoena is granted; a demand for everything is narrowed, after a hearing you paid for.
One appraiser, jointly instructed, is the largest saving in a complex case. Keep the rebuttal right; use it only when the report is wrong.
Pre-tax retirement, Roth, built-in gain and cash are four currencies. A court will not tax-effect without evidence; you can, with a model.
A note for the buyout, an if-as-and-when equity clause, a share of deferred compensation: each is a debt from a moving target. Liens, insurance, reporting and fees for enforcement, in the agreement.
A complex case needs a big firm.
It needs one lawyer who has done it and the right two or three experts. The entourage bills; it does not decide anything.
The tax return is the income.
It is a document prepared to minimize tax. The loan application, the general ledger and the perquisites are the rest of the picture, and the rule requires all of them.
The court will discount the business for the taxes I'd owe on a sale.
Only on evidence that a sale is real and of the rate. An agreement can price it after tax; a hearing usually will not.
My spouse can't touch the company.
The company is valued and its marital share divided; the owner usually keeps it and pays for it. The injunction keeps the business running in the ordinary course while that happens.
The trust my parents set up is off limits.
A vested remainder is property, and its growth during the marriage is marital. A discretionary interest is not. The instrument decides, not the family's expectations.
Once we settle, the numbers are final.
The division is final; an asset misstated or omitted from the disclosures can be reallocated on a motion filed within five years, with no fraud element.
Complexity rewards the side that respects the sequence. Value, characterize, tax-effect, then divide.
Start with a confidential conversation: tell me what the estate looks like →
The law is the same; the proof is not. An ordinary case has two W-2s, a house and two retirement accounts, and the numbers come from statements. A complex case has assets whose character, value and even existence have to be established: a business or several, a partnership interest with capital calls, deferred compensation that vests later, a trust someone else controls, real estate in three states, a portfolio of options. Each one is a small lawsuit inside the divorce, with its own documents, expert and valuation date.
Within forty-two days after service of the petition, without a request: a sworn financial statement and the mandatory disclosures, which include three years of tax returns with all schedules, personal financial statements and loan applications from the last three years, three fiscal years of business financial statements plus year-to-date, real estate and debt documents, investment and retirement statements, bank statements, income documentation and the documents identifying each employment benefit and its value. The duty to supplement continues to the decree, and a spouse who withholds a mandatory item has committed the omission the reopening rule reaches.
Yes, within limits the Colorado Supreme Court set in 2017: the family-case rule contemplates active case management from filing to resolution, with discovery tailored to the needs of the case and proportional to it. A subpoena to the company for the general ledger, financial statements, compensation records and ownership documents is routine; a demand for every email of every officer is not. The court decides on proportionality, and a focused request gets more than a broad one.
It may, in its discretion. The Colorado Supreme Court held that trial courts may choose to apply a marketability discount when valuing a spouse’s interest in a closely held company in a divorce, and declined to adopt a single standard of value. Whether the discount applies, and how large it is, is proved with evidence about the interest, the agreement and the market, not assumed.
It depends on the interest. A vested remainder in an irrevocable trust is property, separate as a gift, with its appreciation during the marriage marital. A purely discretionary interest, or an interest under a revocable instrument someone else can amend, is neither property nor an economic circumstance the court may consider. The trust instrument decides, and the trustee’s records are discoverable to the extent they bear on the interest.
The court cannot itself transfer title to land in another jurisdiction, but it has power over the spouses and can order one of them to sign the deed, with contempt behind the order. For foreign property the decree is drafted around what the other country’s registry will accept, and the alternative is an offset in Colorado assets.
Only on evidence. Colorado courts have refused to reduce values for hypothetical taxes on a sale or withdrawal that is entirely within one spouse’s control and not shown to be imminent, and have reversed tax reductions made without evidence of the amount or the rate. In a negotiated agreement the parties can price every asset after tax, and in a complex estate they should.
The rule sets the skeleton: status conference within forty-two days, disclosures at forty-two days, expert reports fifty-six days before the hearing, discovery closed twenty-eight days before. In the metro districts a contested complex case reaches a permanent orders hearing in nine to fourteen months. Cost is driven by the experts and the discovery fights, not by the lawyers’ hours on the pleadings; a joint valuation expert and a disciplined discovery plan are the two largest savings, and the court can shift fees where the incomes differ.
The next page in this chapter, the pages that belong with it, and the blog posts on the same question.
What you owned before the marriage, inherited, or were given can stay yours. Most claims to it are lost through ordinary household habits rather than through…
Sept 16, 2026RSUs, Bonuses, and Deferred Comp in a Colorado DivorceExecutive pay does not fit neatly into "property" or "income." Colorado law apportions unvested equity, allocates bonuses to when they were earned, and expects…
Sept 17, 2026Dividing Retirement Accounts in a Colorado Divorce Without Blowing Them UpRetirement accounts are often the largest marital asset and the most commonly mishandled. QDROs, Colorado PERA, the time-rule formula, and survivor benefits each…
A consultation is a working session, in person in Greenwood Village or by video: bring the entity chart and the last returns, and I will tell you what has to be proved, by whom, with which expert, and in what order. Your note reaches my office directly; during business hours we call you back within the hour, run the conflicts check, and set the meeting.
Talk to us about your case.
303-507-5529One call. A real person picks up, hears you out, and tells you how we would handle what you are facing and what to do first. No phone tree, no sales pitch, no obligation. Your first conversation is with our intake paralegal, who will get you to Aaron fast.
Rather write? Send a short note and during business hours we call you back within the hour.